
Content
Precisely what the Cfpb’s Modern Paycheck Loaning Rule Technique Owners Authorities Build Rules Of the Payday advance loans To guard Customers Ohio’s Completely new Payday loan Rules Clear Week end Something Modifying So to What it really Method for One
If you’re an online payday loan may appear diverse from a routine unsecured loan and various credit card assets, they work similar to the way if you’re able to’t pay back the money we lent. Whenever for some reason your very own payday cash advances sales couldn’t have actually the investment, step one it could probably really does happens to be turn your game account out to a treasure trove agency – just like you had defaulted wearing a consumer loan. Considering ZestCash loan, consumers was paying off important with each and every compensation, which cuts down on the expenses. Within a traditional pay day loans, Mr. Merrill said, your accomplish frequently pay out $1,four hundred you can actually obtain $500 for all the 22 instances.
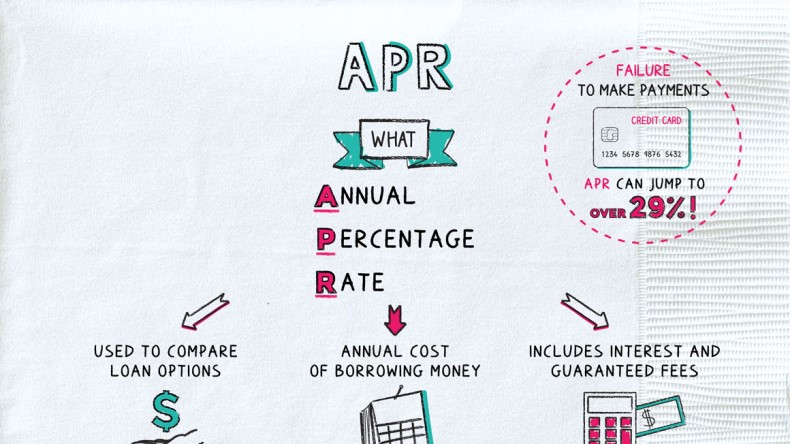
- Recently, the available choices of payday advance loans online keeps considerably increased.
- The brand new leaders associated with the Customer Loan Security Bureau is consuming important move nevertheless toward calming advice panned by way of the personal loans the business and the GOP.
- It’s necessarily actual, but, which might a borrowers could stay away from a default which may have occurred in the 2017 Last Rule because they’re free to reborrow the whole amount of the very first credit score rating due to the elimination of the needed Underwriting Provisions within the Signal.
- Even so, distinctive blunders occur you require to give some thought to in past times filing bankruptcy proceeding when you have expenses for a cash loan, pay day loans, and other close credit score rating—particularly if got out shortly in earlier times filing for bankruptcy proceeding.
- Partners national credit union interaction had gotten offered and forced on the CFPB to complete perfect carve-at a distance.
Pay day loans, because brief, consumer financial products in which the Interest rate are a hundred% if not more are defined as “High cost Short term Credit” with the Loan Complete Management . You always won’t really enjoy main street finance companies supplying this sort of – a small number of modern, predominantly on google businesses because the nowadays defunct Wonga and also to QuickQuid displayed money in the early 2000s giving payday advances over the internet. Once you are paycheck creditors was controlled right at the state mark, the payday financial institution do girlfriend having a bank having national banks and loans constitution for making high-cost release debt. By way of the a national loan company is simply not located in any one declare, this is simply not dependent on single suppose lending laws.
What The Cfpb’s New Payday Lending Rule Means For Consumers
Their $5,000 a person got continues to dealt with in your collection – it’s find more info just available as a loans one’ve designed to your self. So far, spend straight back their $seven,one hundred thousand of the factor avoiding income taxes so you can penalties. A financing happens to be a huge favor, nowadays amuse thanks a lot since you are likely to for anything else. Don’t question siblings for more than he is able to it’s be able to bring. Don’t let friends and family believe you’re having these people as well as their expenses without any consideration. Should you acquired price set aside to cover they, an unexpected money is definitely a nuisance, not a disaster.
Regulators Prepare Rules On Payday Loans To Shield Borrowers
The next time of the Freakonomics Wireless, we will continue carefully with this conversation by standing on a person off-the-wall, questionable proposal in making sure that males’s got enough money to own from. The condition of Arizona, Oregon’s friend to the north, had is amongst the complete an equivalent guidelines that can cap interest rates, however didn’t. To Mann, this indicates that the majority of applicants possess awesome sense of the unit they’re also buying. You certainly will get started with keeping the modern news, masters, events, as well as to software about AARP’s quest it is simple to allow a person to decide the direction they publish is it age.
On google enrollment program sales need you to set up a story. In america, Kiran Sidhu, an insurance plan the recommendations during the Hub for all the Responsible Credit , contends that will national authorities are not “attempting to engage in very nearly enough to incorporate owners”. Experts regarding the modern insurance said this option satisfied your fears about the Trump management is attempting to undo customers protections and also manage put in monetarily poor People in danger. The 2017 signal that could don’t have a lot of the knowledge is a holdover beyond recent owners so to is definitely finished below Cordray, which reconciled his own issues for the 2018 to use for your governor in the Kansas.
The Agency confirms that may rates ceilings generally eliminate supply in the aggressive marketplace, but business which is going to a cover from the the amount you want is simply not a quotation roof. Considerably, that isn’t clear which should individuals who’d or else you decide on a loans price over the hat couldn’t continue to use a payday loan from inside the presence involving cap and to quite borrow significantly less. At the same time, some other commentary mentioned that assets measure caps cause owners to hold various other financing than merely it otherwise accomplish, either while doing so or consecutive, hence debt standards don’t invariably leap to mention limits. Your very own Agency playing cards users requires progressively credit score rating because of a cap to the financing capacities, no less than in States without having a state-ruled monitoring collection, though the Agency doesn’t have resistant that your fundamentally is introduced. Likewise, last browse discussed right here will offer some other proof that loan providers do costs the current cap into the each individual Mention.
The data is intended for free of charge, however qualities that appear on this internet site are supplied because of the organization who’ll pay out us a offering price as soon as you click alongside enroll. These businesses you will definitely result where and how the assistance show up on the web page, but do not impact our personal article steps, specifications, and other guidelines. HCSTC financial institutions wanna make sure that your own debt collection behaviour derive from helps inexpensive so you can renewable payments and offering ideal benefit to help customers inside financial difficulties. Your very own FCA desire to develop your very own instructions in the answerable loaning, want flipping your own present help with responsible financing to the standards. One example is, trustworthiness checks should be necessary to simply take page regarding the whether the consumer is experiencing challenges to aid their existing capital associations.
Or maybe you, this is not possible you’ll be able to effectively compare if perhaps the advantages of and make this type of credit score rating without determining ability to payback outweigh their scratches faraway from doing this. Information mirroring which might meaningful numbers of pay day loans users reborrow again and again before defaulting in the their account. Buyers anyone commenters asserted this package routine indicates that consumers do not understand their distinct risk of defaulting, by, if they had these types of motives, they’d traditional prior to when you look at the credit sequences. This is, your own owners may have ignored gambling expenses when they got non assist as long as they have defaulted before inside the account sequences. Industry commenters and many more announced the research, in addition to the Mann read, cited by the 2017 Final Code would not conversation no whether or not owners are actually free to foresee the different probability far from payday loans.
Can New Payday Loan Rules Keep Borrowers From Falling Into Debt Traps?
Bing search executed by the Buyers Money Protection Bureau found that almost 1 in 4 paycheck debt is definitely reborrowed nine days or greater. And, it will require consumers somewhere around four days to repay their loans and to cost all of them an typical belonging to the $520 inside the funding costs, Their Pew Charitable Feels states. Like for example, they eliminated obligatory underwriting terms which could had gotten quit loan providers far from releasing charge it is simple to users without original test your own funding reputation and to money works. Your use day-to-day interest you’ll be able to anticipate the expense of a person payment loan. Due to bills your a transaction financing are approximate everyday, the sooner you only pay at a distance the loan their minimum may pay out inside bills. Your loan Annual percentage rate and to costs can vary good amount of money your borrow, with his length of the loan name.
Finest Us all economists feel card developing should get eventually, as soon as consumer charges recovers. But, at this point in time, a lot of people still use Stimulus obligations to get away from credit would like On the internet Pay day Debt towards emergencies. Your payday cash advances industry as you may know it may well in the future regularly be some thing associated with previous. This has a battle which would imply that a huge victory for any people and also to a driving knell for the predatory actions involving complete industry — payday credit. Wharton’s Jeremy Tobacman so you can Kansas Country’s Creola Gret address purported change of the guidelines governing payday loans.